Housing Market Snapshot: Northern California Foothills & Northern Nevada – September 2026
Housing Market Snapshot: Northern California Foothills & Northern Nevada – September 2026
The housing markets across Nevada, Placer, El Dorado, Sacramento, Yuba, and Sutter counties in California, along with Washoe, Carson City, and Douglas counties in Nevada, sit in a balanced-to-mildly seller-leaning environment as of late summer 2026. Prices are largely stable or showing modest year-over-year gains rather than sharp declines. Inventory remains constrained enough to support sellers who price realistically, while buyers enjoy more choice and negotiating room than during the peak frenzy years of 2021–2022. Elevated mortgage rates continue to act as the primary brake on demand.
This is neither a deep buyer’s market with widespread price cuts nor an ultra-competitive seller’s market. Well-priced homes still move, often near asking price, but overpriced listings sit longer and frequently require reductions.
California Counties: Stability with Local Nuance
California Association of Realtors (C.A.R.) data through August 2026 shows the broader state market rebounding slightly in sales and prices after a softer July, even as rates stayed elevated. In these specific counties, the picture is one of resilience tempered by rate sensitivity and seasonal patterns.
Sacramento County
August median existing single-family price: $549,000 (up 1.7% from July’s $540,000; roughly flat year-over-year at –0.2%). Sales dipped month-over-month but held or improved slightly versus 2025 in some comparisons. Unsold inventory index around 3.2 months and median time on market near 25 days point to conditions that still favor sellers modestly, though the gap between list and sale prices has widened in places. Buyers find more selection than a year or two ago, especially on homes that need work or are priced aggressively.
Placer County
August median: $692,500 (up slightly from July; +2.6% year-over-year). Sales volume softened in August but remained positive versus the prior year in earlier periods. Days on market often in the low-to-mid 30s. The county continues to attract buyers seeking suburban and foothill lifestyles, keeping demand steady relative to available homes.
El Dorado County
August median: $690,000 (down from July’s stronger $735,000 reading but still +1.5% year-over-year). Sales declined in August. Higher inventory index (around 4.9 months) and longer days on market give buyers more breathing room, particularly outside the most desirable Tahoe-influenced or higher-end pockets. Pricing discipline matters more here.
Nevada County
August median: $530,000 (down from July; –5.4% year-over-year). Sales improved month-over-month. Inventory and days on market are higher than in tighter neighboring markets, creating a more balanced feel. Negotiation opportunities exist, especially on homes that have been listed longer.
Yuba and Sutter Counties
These more affordable markets show relative strength. Yuba’s August median was about $452,500 (+2.8% year-over-year) with solid sales gains. Sutter’s median hovered near $438,400 (essentially flat year-over-year) with rising sales volume. Both benefit from lower price points that keep more buyers in the game, resulting in balanced conditions with healthy activity.
Across the California group, months of inventory generally range from the low 3s to mid-4s or higher in some foothill areas—enough to prevent bidding wars on every property but not so high that prices are under broad pressure. Sale-to-list ratios frequently land near or above 98%.
Northern Nevada: Tighter Supply, Firmer Prices
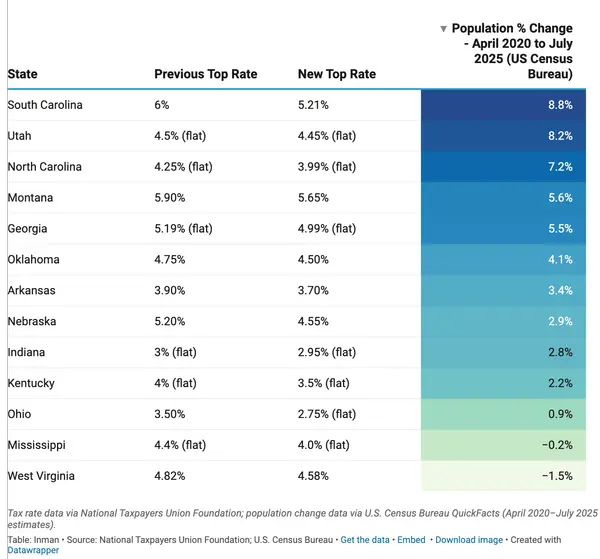
Washoe, Carson City, and Douglas counties have generally held up better on price than many Western markets, supported by ongoing in-migration, limited new supply, and Nevada’s tax advantages.
Washoe County (Reno/Sparks)
Recent median sale prices have tracked in the mid-to-high $500,000s, with year-over-year gains in the low single digits in multiple data sets (Zillow typical home value around $572,000, +1.6% year-over-year as of late August). Inventory has repeatedly run 20–30% below year-ago levels in 2026 reports, keeping months of supply low (often near or under 2 months for single-family homes in earlier snapshots). Homes continue to sell relatively quickly when priced correctly, and the market retains a clear seller lean.
Carson City
Typical home values hover near $500,000–$520,000 range with modest appreciation. The market is more mixed by price segment—tighter at the lower and mid levels, with more inventory and negotiation room higher up. Government employment provides a stable demand base.
Douglas County
Higher price points (recent three-month medians near $738,000 in some reports, with stronger year-over-year gains) reflect Tahoe proximity and Carson Valley appeal. Days on market tend to run longer than in Washoe, and sale-to-list ratios sit near 98%. Demand remains solid enough to support prices, though buyers have leverage on slower-moving or luxury listings.
What This Means for Buyers and Sellers
Buyers have more options and time than during the height of the post-pandemic boom. Price reductions appear on a meaningful share of listings (often 20–30% in metro-level data), and competition has cooled enough that multiple-offer situations are less automatic. The trade-off is higher monthly payments driven by rates that have stayed elevated through much of 2026. Affordability remains the biggest hurdle, which is why lower-priced counties (Yuba, Sutter, parts of Sacramento) and well-located entry-level homes see steadier traffic. Cash or strongly qualified buyers retain an edge.
Sellers still benefit from structurally limited inventory in most of these counties. Homes priced in line with recent comparable sales typically sell in a reasonable timeframe and close near asking price. Those chasing peak-era numbers or ignoring condition and location face longer marketing periods and eventual reductions. Northern Nevada, particularly Washoe, has offered more consistent price support than many California peers.
Bottom Line and Outlook
These markets are in a holding pattern of relative stability. Demand exists, supply is not abundant, and rates keep a lid on explosive growth. Expect seasonal softening into fall and winter, with potential for modest price moderation if rates stay high or inventory builds. A meaningful drop in rates would likely re-accelerate activity quickly given the underlying demand from California out-migration and regional job bases.
Local conditions vary significantly by neighborhood, price point, and property condition. County-wide medians mask important differences—consult recent comparable sales and a knowledgeable local agent for decisions on specific properties. Data is drawn primarily from California Association of Realtors county reports through August 2026, Redfin, Zillow, and Northern Nevada regional sources.
Recent Posts